
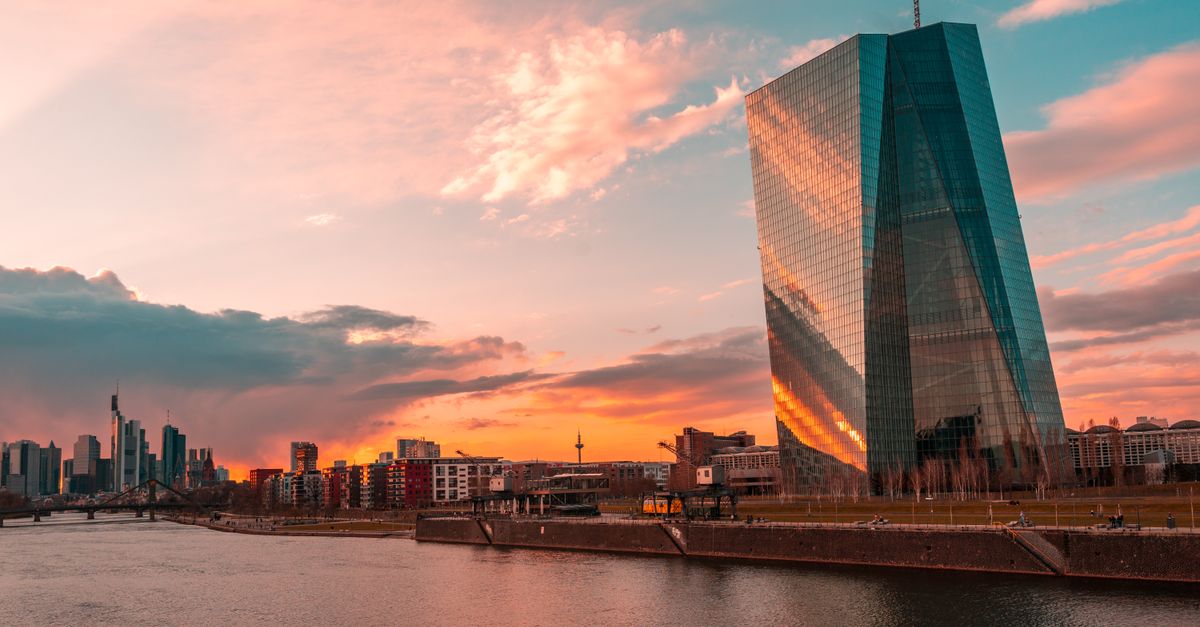
The European Central Bank will start investing a slice of its own funds in tokenized public-sector securities, settling those trades in central bank money through Pontes, a new Eurosystem platform for distributed-ledger transactions. The announcement, made Tuesday, comes a day after Pontes itself went live, and it marks a rare instance of a major central bank stepping into a market not just as regulator or infrastructure provider, but as an actual buyer.
The move is deliberately modest in scale. The ECB has said the purchases will represent only a small portion of its own funds, and no specific euro amount has been disclosed. The money will not come from monetary policy operations but from a separate, non-monetary-policy portfolio that generates income used to cover the ECB’s own operating costs. In other words, this is not stimulus, liquidity provisioning, or anything resembling quantitative easing. It is closer to a pilot investment, structured to generate real operational experience with tokenized instruments while the assets themselves stay conservative: euro-denominated securities issued by euro-area central and regional governments, public agencies, and European supranational institutions.
Why Pontes Matters Here
Pontes is the connective tissue that makes this experiment possible. Described by the Eurosystem as a bridge between emerging DLT platforms and established central bank infrastructure, it is designed to ensure that as securities markets tokenize, settlement can still happen in central bank money rather than in some privately issued substitute. That distinction is not a technicality. Central bank money carries no credit risk and no counterparty risk in the way commercial bank money or stablecoins can, and preserving its role in settlement has become a quiet but persistent policy priority across the Eurosystem as tokenization spreads. Readers who want the mechanics of the platform itself can find more detail in the ECB’s launch of Pontes to settle tokenized assets in euros, published the day before this announcement.
What makes Tuesday’s news notable is that the ECB is not simply hosting the rails, it is riding them. By becoming a buyer on a system it also operates, the ECB is placing itself in a dual role that has already drawn attention, as described in coverage of the ECB acting as both operator and buyer in the new tokenized bond system. Central banks are typically wary of blurring lines between infrastructure provision and market participation, so the decision to do both here, even at small scale, signals how seriously the institution is treating the shift toward tokenized securities.
What This Signals for Markets
For an institution as procedurally cautious as the ECB, the choice to become a direct participant, however small, is itself a message. It suggests the central bank wants firsthand operational knowledge of how tokenized government and supranational debt actually settles, clears, and behaves under real market conditions, rather than relying solely on pilot programs run by commercial banks or fintechs. That kind of hands-on exposure can inform future decisions about how far the ECB is willing to go in supporting tokenized market infrastructure at scale.
It also fits into a broader pattern of European monetary authorities positioning themselves early in the tokenization debate, even as they remain cautious on adjacent fronts. Just this week, national central banks within the European System of Central Banks pushed back on parts of the bloc’s stablecoin framework, arguing that MiCA’s reserve rules need revision, a debate detailed in reporting on central banks urging an overhaul of MiCA’s stablecoin deposit rules. Together, these developments show a central banking system that is simultaneously experimenting with tokenized settlement rails while trying to tighten the rules around privately issued digital money.
The context here is not limited to Europe. Central bank digital currency projects globally have faced growing scrutiny, including geopolitical retrenchment, as seen when Saudi Arabia stepped back from the China-backed mBridge CBDC initiative. Against that backdrop, the ECB’s approach, quietly building settlement infrastructure and then testing it with its own balance sheet, reads as a deliberately cautious, incremental strategy rather than a grand CBDC rollout.
What Comes Next
Several practical details remain unsettled. The ECB’s Executive Board has yet to determine the timing and precise operational parameters of the purchases, pending the conclusion of preparatory work. Observers should watch for:
- Confirmation of which specific euro-area or supranational issuers are first to see their tokenized debt purchased by the ECB.
- Any disclosed figures once purchases begin, since the current announcement gives no concrete euro amount.
- Whether Pontes expands beyond this pilot use case to accommodate a broader range of DLT-based settlement activity across the Eurosystem.
- How this pilot interacts with the ECB’s parallel digital euro work, given that both initiatives touch on the future architecture of central bank money.
For now, the ECB is proceeding carefully, treating tokenized securities as a space to learn from rather than a market to dominate.
Source: Cointelegraph
This content is for informational purposes only and does not constitute financial or investment advice.
Create a free account to comment and earn rewards.
Create account Log in